Stress-Testing Portfolio Basic
Stress-testing means analyzing a portfolio under extreme but plausible scenarios. For instance, imagine a sudden 20% drop in the S&P 500 or a spike in inflation to 8%. These conditions reveal how vulnerable your investments really are, instead of just trusting historical averages or recent performance.
Stress tests have roots in banking regulation, where firms showed resilience during the 2008 crisis or the 2020 pandemic. Yet, individual investors often skip this step even though a simulated 15% downturn happens roughly every decade. The result? Many portfolios crack when markets sour.
One simple practical example: if your portfolio loses 15% in a market shock, how long does it take to recover? Will dividend income cover your withdrawals, or do you erode principal?
Stress-testing isn’t just about losses. It also captures liquidity shortfalls, concentration risks, or correlated asset behavior. You need that kind of perspective to manage risk beyond volatility numbers.
Common Pain Points
Many investors believe diversification means immunity. That's wrong. Owning a dozen stocks in tech won’t help much if the whole sector sinks on regulatory crackdown.
Ignoring tail risk leads to an illusion of safety. The problem intensifies when investors fail to consider macroeconomic shifts like rising rates, geopolitical events, or credit crunches. These often hit portfolios simultaneously.
Another mistake: relying on historical market correlations that break down in crises. For example, in the 2008 crash, equities and corporate bonds fell together despite usual inverse moves.
Consequences vary: portfolio drawdowns bigger than planned, forced selling at bottoms, or missing capital for opportunities. This drains returns and confidence.
Consider a retiree funded for a 3% withdrawal rate but unaware that a stressed 2008-like scenario might require cutting expenses drastically to avoid running out of money.
Steps to Stress-Test
Scenario Simulations
Pick predefined adverse events like stock market crashes (-15% to -40%), bond sell-offs, inflation spikes (+5%+), or currency shocks. Use tools like Portfolio Visualizer or Riskalyze for automated scenario stress tests. They show portfolio impact numerically in terms of drawdown and recovery years. This approach forces an explicit risk view.
Historical Replay
Apply past market crises to your portfolio's historic holdings. For example, run a 2008 financial crisis replay using data sources such as Bloomberg Terminal or Yahoo Finance. This identifies which assets tanked, how correlated losses summed up, and reveals hidden threats like concentration risk. Practical and eye-opening.
Factor Analysis
Break exposure by risk factors like interest rate sensitivity, value/growth tilt, or sector weights. Factor stress tests can isolate the influence of inflation on bonds or impact of recession on cyclicals. Morningstar Direct offers such capabilities. This method reveals vulnerability beyond asset class level.
Liquidity Assessment
Stress tests must include liquidity considerations. Under pressure, can you sell assets without major discounts? Use bid-ask spread analysis, trading volume data, or tools like FINRA’s Trade Reporting Facility. Illiquid holdings like private equity or thinly traded ETFs falter in shocks and hamper portfolio rebalancing.
Monte Carlo Simulations
Monte Carlo incorporates randomness and multiple risk parameters to generate thousands of investment paths. Using software like MATLAB or R packages, you can estimate probable losses at percentiles such as a 5% worst-case. Be cautious: model assumptions may blindside if you omit fat tails or structural breaks.
Stress Testing Software
Professional platforms like FactSet, MSCI RiskMetrics, or open-source R stress-test modules bring sophistication but often have a learning curve. For retail investors, simpler Excel-based stress-testing templates (e.g., from CFA Institute) can suffice if used thoughtfully.
Sensitivity to Withdrawals
Focus on how cash flow demands impact portfolio stress response. Simulate higher withdrawal rates in downturns using tools like FIRECalc. You’ll see exactly when portfolio depletion accelerates. This stresses the connection between portfolio value shocks and real spending needs.
Correlation Breakdown Tests
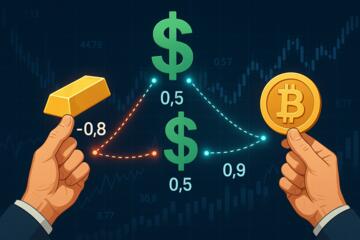
Introduce hypothetical correlation breakdowns across holdings, increasing asset price covariance during crises. This reveals risks hidden by stable long-term correlations. Testing this manually requires adjusting covariance matrices or using software like Palisade’s @Risk.
Leveraged and Margin Impact
For those who borrow against portfolios, stress tests must factor margin calls. What if portfolio declines 25% while interest rates rise 2 points? Calculate forced sales and resulting tax implications. This rare step is often ignored but critical for leveraged investment plans.
Mini-Case Examples
Case One: A mid-size tech fund held 70% equities, 20% bonds, 10% cash. They ran a 2008 crash replay using Portfolio Visualizer. The test revealed total portfolio loss of -33%, longer recovery (6+ years) than expected, and bond losses underestimated. After adjustments, they reduced equity exposure to 50%, extended duration on bonds, and increased cash to 20%. The next similar stress, hypothetical -28%, showed only a 15% loss and recovery in under 3 years.
Case Two: A self-directed retiree portfolio heavily weighted in REITs and corporate bonds conducted liquidity stress tests via FINRA data. The analysis highlighted potential asset illiquidity during tightening. Rebalancing to include more Treasury securities produced a simulated drawdown improvement from 30% to 18% in a stress runoff.
Stress-Test Checklist
| Step | Action | Purpose | Tools |
|---|---|---|---|
| 1 | Collect portfolio data | Establish baseline holdings | Broker statements, software exports |
| 2 | Define stress scenarios | Target realistic shocks | Portfolio Visualizer, manual definitions |
| 3 | Run historical replay | Learn past losses | Bloomberg, Yahoo Finance |
| 4 | Assess liquidity | Check sell feasibility | FINRA data, volume analysis |
| 5 | Analyze factor risks | Identify hidden drivers | Morningstar Direct |
| 6 | Model withdrawals | Stress cash flow | FIRECalc, spreadsheets |
Stress-Test Pitfalls
Don’t run stress tests only once. Market dynamics shift, and portfolio compositions change over time, so stress scenarios need updates annually or after major events.
Ignore scenario bias that favors “average” downturns. The 2020 pandemic crash, for instance, came suddenly with sharp rebounds, unlike drawn-out bear markets.
Relying solely on software presets frustrates some. They don’t always reflect personal exposure nuances or tailor for individual goals.
Overlooking taxes and transaction costs during forced rebalancing often skews projected outcomes.
And avoid treating simulations as crystal balls. They reveal vulnerabilities but do not predict exact future paths.
FAQ
What is the best frequency for stress tests?
Run stress tests once a year or after major portfolio changes or market events. This helps catch new vulnerabilities as conditions evolve.
Can I perform stress tests without software?
Yes, by manually applying historical market drops to your portfolio holdings and calculating impact, although software improves speed and accuracy.
How does stress testing differ from diversification?
Diversification reduces idiosyncratic risk but stress testing examines portfolio behavior under extreme conditions, including systemic correlations and liquidity limits.
Do stress tests predict future losses?
No. They model hypothetical adverse events to expose weaknesses—not exact forecasts. Use them as risk insight tools.
Which assets need most scrutiny?
Illiquid holdings, leveraged positions, and concentrated sector bets require deeper stress-testing focus due to their outsized impact during crises.
Author's Insight
From personal experience, I found stress-testing reshaped how I structure portfolios. It forced me to challenge assumptions about risk tolerance and recovery time. Simple scenario simulations often exposed my blind spots around correlation and liquidity. My advice: start small with scenario replays and build complexity gradually. Also, sharing stress-test outcomes with a trusted advisor sharpens perspectives. Stress testing is not prediction but preparation—and that mindset shift alone improves decisions.
Key Takeaways
Stress-testing your portfolio uncovers hidden vulnerabilities by simulating extreme events and liquidity challenges. Skipping this work risks painful surprises when markets shift. Use available tools to run scenario analyses, historical replays, factor breakdowns, and withdrawal stress tests. Update tests regularly, and beware overly optimistic assumptions. The goal: design investment plans that withstand downside shocks and survive until opportunity returns.