Learning Asset Allocation
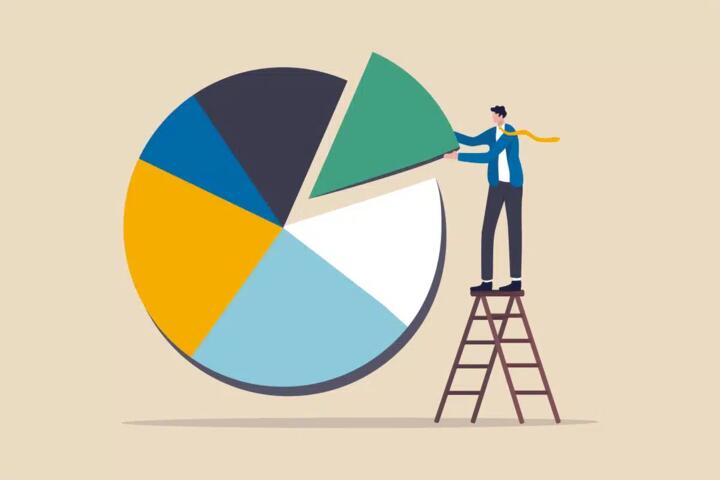
Asset allocation refers to dividing your investment portfolio across different asset categories, such as equities, fixed income, real estate, and cash. For example, a classic approach might assign 60% to stocks and 40% to bonds. According to a 2023 survey by Vanguard, about 64% of investors use strategic asset allocation as their baseline. This means they fix a target mix and rebalance periodically rather than chasing market timing. Proper allocation seeks to balance risk and reward aligned with financial aims.
This is not guesswork, but a structured plan that considers your current situation and objectives.
Common Allocation Pitfalls
Many investors treat allocation patterns like trends, moving heavily into equities after rallies and pulling back after declines. This behavior leads to poor timing and losses. Ignoring your risk tolerance or time horizon produces allocations that either expose you to unnecessary volatility or prevent growth. For instance, retirees who keep 90% in stocks often face steep drawdowns, threatening income streams. Weak allocation often results in portfolio stress, missed goals, and suboptimal returns.
They pick strategies without reviewing lifestyle changes.
Practical Allocation Tactics
Define Your Investment Horizon
Start by establishing how long you intend to invest. If retirement lies 25 years ahead, equities can play a larger role since you have more time to recover from downturns. Short horizons, like five years, call for conservative mixes leaning on bonds and cash equivalents. Fidelity reports portfolios with longer horizons achieved 7-8% average annual returns over a decade versus 3-4% for conservative blends.
Assess Your Risk Appetite
Risk tolerance isn’t guesswork; quantify it using questionnaires or apps like Riskalyze. After completion, you might learn your comfort zone corresponds to a 70/30 stock-to-bond mix. This alignment ensures you won't react emotionally to swings. In practice, that means not selling when the market drops 15%—because the plan factored in such volatility.
Use Diversified Asset Classes
Avoid concentrating investments in a single sector or geography. Instead, add international stocks, real estate investment trusts (REITs), and possibly commodities. For example, including a 10% REIT allocation can improve overall portfolio Sharpe ratio, meaning better risk-adjusted returns. Vanguard Total Stock Market ETF (VTI) combined with Vanguard Real Estate ETF (VNQ) illustrates accessible diversification for retail investors.
Periodic Rebalancing
Rebalancing corrects drift from your target allocation caused by market moves. Suppose your stocks rise to 70% from a 60% target; selling equities to buy bonds keeps risk consistent. Rebalancing once or twice a year works well—too frequent trades generate taxes and fees. Charles Schwab's Intelligent Portfolios automate this, reducing friction for users.
Mind Tax Implications
Asset locations—taxable vs tax-advantaged accounts—affect allocation choices. High-yield bonds generate ordinary income, best placed in IRAs or 401(k)s. Stocks with long-term gains often fit taxable accounts to benefit from favorable tax rates. Software like Personal Capital tracks tax impact, helping adjust allocation in real time.
Integrate Alternative Investments
Alternatives like private equity, hedge funds, or cryptocurrencies can diversify but bring complexity and illiquidity. Most portfolios hold no more than 5-10% here. BlackRock’s Aladdin platform offers risk analytics that justify allocations to alternatives based on expected return and drawdown scenarios. For retail investors, funds like iShares Blockchain ETF (IBLC) provide a liquid, lower-cost exposure.
Adjust for Life Events
Marriage, home purchase, job changes, health shifts often warrant allocation tweaks. A 45-year-old who buys a house and starts a family may need to reduce equity exposure slightly and increase bond holdings to balance new financial responsibilities. Tracking these adjustments keeps your portfolio aligned with real-life goals instead of static models.
Set Realistic Return Expectations
Don’t chase 15% annual returns while holding 60% bonds. Historically, U.S. stocks returned around 10% annually, bonds 3-4%. Overestimating returns risks aggressive positions mismatched to patience or timeline. Morningstar’s portfolio simulator lets you test iterations before committing actual capital.
Leverage Professional Advice
Financial advisors or robo-advisors help calibrate allocation to your unique profile. Hybrid models like Betterment or Personal Capital mix algorithms and human advice, often bringing personalized scenarios and emotional control. Their data-driven approach cuts bias that individual investors frequently exhibit.
Real-Life Allocation Cases
Case 1: Tech Firm CEO, aged 40 — Initially kept 90% in tech stocks. After a market correction in 2022 causing a -25% drop in portfolio value, they diversified to 50% stocks, 40% bonds, 10% alternatives. Within 18 months, volatility dropped by 30%, and returns stabilized around 7% yearly.
Case 2: Retiree Couple, 68 — Held 70% stocks, 30% bonds, causing portfolio swings leading to emotional withdrawals. They shifted to 40% stocks, 50% bonds, and 10% cash. This reduced portfolio drawdown risk by over 20% during volatile periods and increased income security from bond coupons.
Allocation Checklist
| Step | Action | Goal | Tool/Resource |
|---|---|---|---|
| 1 | Estimate time horizon | Set duration | Financial Goal Tracker |
| 2 | Measure risk tolerance | Avoid emotional trades | Riskalyze quiz |
| 3 | Select asset classes | Diversify exposure | Vanguard ETFs |
| 4 | Rebalance portfolio | Maintain risk level | Schwab Intelligent Portfolios |
| 5 | Adjust for taxes | Maximize after-tax returns | Personal Capital |
| 6 | Incorporate life events | Stay relevant | Annual review |
Allocation Mistakes
Overconcentration in one asset class remains common; I've seen portfolios with 85% in tech stocks, ignoring the 2000 dot-com crash lessons. Emotional rebalancing after sudden drops is a frequent error, cutting gains short. Ignoring tax efficiency drags net returns down by 1-2% yearly, which accumulates. Lastly, neglecting periodic review fails to reflect changing financial circumstances and market environments.
Stick to the plan more.
FAQ
How does age affect asset allocation?
Age generally guides risk exposure; younger investors tolerate stocks better, while older ones should increase bonds. The common rule subtracts age from 100 to find stock allocation, but personal risk changes those targets.
Should I include international assets?
Yes, adding 15-25% international exposure improves diversification and hedges domestic downturns. Emerging markets ETFs like iShares MSCI EM (EEM) offer growth potential but with added volatility.
How often should I rebalance?
Annual or semi-annual rebalancing suffices for most. More frequent adjustments trigger extra costs without significant risk improvement. Use automated tools to simplify.
Can I rely on robo-advisors for allocation?
Robo-advisors provide data-driven allocation with minimal effort and adjust based on your inputs. However, reviewing assumptions periodically keeps your goals aligned.
What mix works for conservative investors?
Typically, 20-40% equities combined with 60-80% bonds and cash suits conservative profiles, focusing on capital preservation over growth.
Author's Insight
I've watched portfolios tank after ignoring risk tolerance or failing to rebalance. Early in 2023, I adjusted a client’s portfolio from 75% growth stocks to 60/30/10 across stocks, bonds, and alternatives, which better weathered market dips. Experience proves that knowing your capacity for stress is just as important as the math behind allocation. Use tools, but trust your judgment; data guides, you decide.
Key Takeaways
Asset allocation shapes how your money grows and survives downturns. Identifying your horizon and risk appetite sets a realistic foundation. Diversifying across asset classes and rebalancing periodically keeps your portfolio aligned with goals. Watch taxes and life changes to update your approach over time. Above all, stick to plans crafted from real data, avoiding emotional reactions that cost returns.